
Unlock up to 90% of your Property Value
Your property is one of Singapore’s most valuable assets, and it doesn’t have to sit idle. At ThinkSME, we help Singapore SME owners use property cashout to release equity from their private residential, commercial, or industrial property and convert it into working capital for your business.
Property cashout in Singapore is one of the most flexible and cost-effective financing solutions available to SME owners.






What is Property Cashout in Singapore?
Property Cashout Singapore allows you to unlock the equity in your property without selling it. Through cash-out refinancing, you can access additional funds while continuing to own your residential, commercial, or industrial property.
Ideal for SME owners, property cashout provides lower interest rates, larger loan amounts, and flexible funding for business expansion, working capital, equipment purchases, or investment opportunities.
Example Calculation
If your commercial shophouse is valued at S$2,000,000 and you have an outstanding mortgage of S$900,000, you may be able to access up to S$900,000 in additional cash through a property cashout refinancing, without selling the property.

Formula: (S$2M × 90% LTV) − S$900K outstanding = S$900K cashout available

Property Cashout vs Traditional Mortgage Refinancing

Purpose
Unlock your property’s equity to raise funds for business expansion, working capital, investments, or personal financial goals.

Purpose
Refinance your existing mortgage to secure a lower interest rate or reduce monthly repayments.
Cash Received
Receive additional cash by borrowing against your available property equity.
Cash Received
No additional cash received. Your existing mortgage is simply replaced with a new loan.
Loan Amount
Borrow up to 90% of your property’s valuation (subject to eligibility and lender assessment).
Loan Amount
Limited to your existing outstanding mortgage balance.
Interest Rate
Competitive secured financing rates, typically around 1.5%–3.5% p.a., depending on lender and profile.
Interest Rate
Focused on obtaining the lowest available mortgage interest rate for your existing loan.
Loan Tenure
Up to 15 years for business financing (subject to lender’s terms).
Loan Tenure
Up to 30 years, depending on property type and borrower eligibility.
Processing Time
Approval and disbursement can be completed in as fast as 1 week.
Processing Time
Typically 4–12 weeks, depending on valuation and bank processing timelines.
Financing Options
Access to 60+ banks, financial institutions, digital banks, and private lenders to secure the most suitable financing package.
Financing Options
Usually limited to traditional local and international banks offering mortgage refinancing.
Best For
Business owners and property investors who need additional capital while retaining property ownership.
Best For
Homeowners looking to reduce mortgage costs without accessing additional funds.
How Does Property Cashout Work in Singapore?
ThinkSME guides you through every step, from free consultation to cash in your account.
-
Property Valuation
A bank-appointed valuer determines your property’s market value and maximum loan amount.
-
Assess Equity
We calculate: (Property Value x up to 90% LTV) minus outstanding balance = your available cashout.
-
Choose Lender
ThinkSME compares 60+ banks and institutions to find your best rate, LTV, and terms.
-
Submit Docs
Provide the property address and documents. ThinkSME prepares and submits your full application.
-
Approval & Drawdown
We provide approval-in-principle quickly. Full approval and disbursement within 2–7 working days.


Types of Property Eligible for Cashout in Singapore
ThinkSME works with all major private property types in Singapore for equity withdrawal.
Private Residential
Up to 85%
Condominium, Landed, SOHO
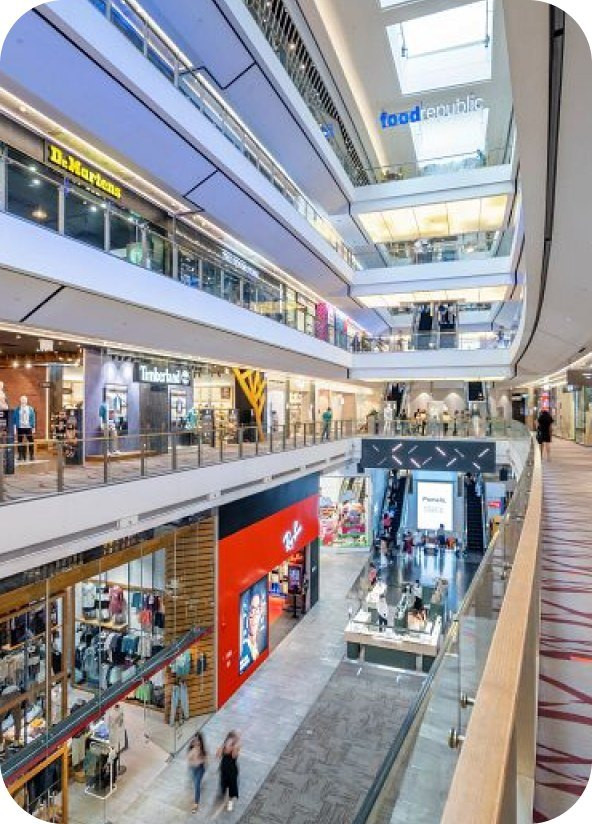
Commercial Property
Up to 75%
Shophouse, Retail, Office unit
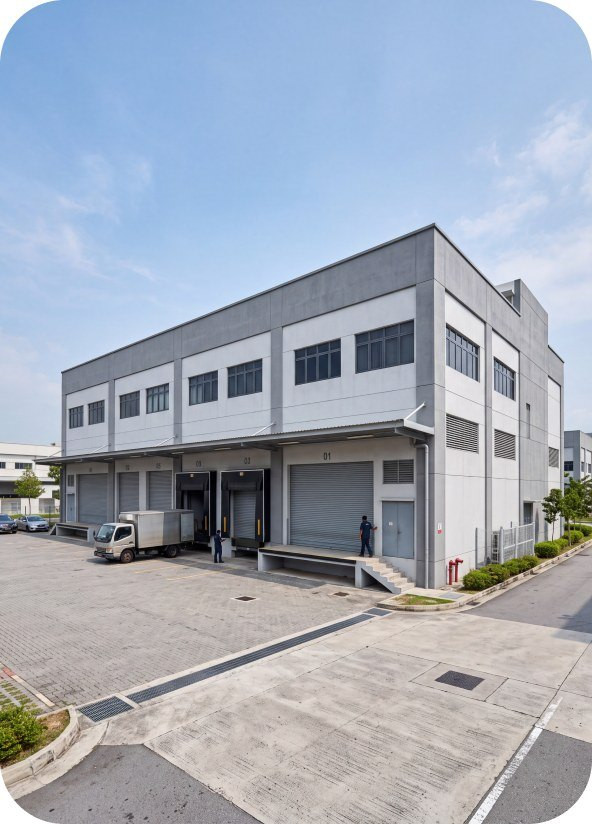
Industrial Property
Up to 75%
B1/B2 Factory, Warehouse, Ramp-up
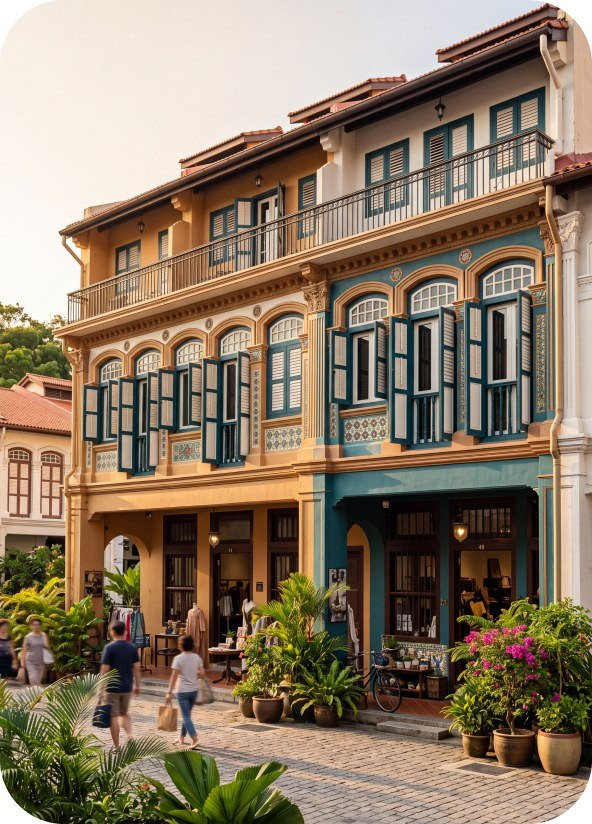
Mixed-Use
Up to 80%
Heritage shophouse, HDB shophouse, Mixed retail-resi
Key Benefits of Property Cashout for Singapore SMEs
-
Lower Interest Rates (Bank Rates)
Secured property loans carry rates from 1%+ p.a. vs 4–5% p.a. for unsecured SME loans, significantly reducing your cost of capital.
-
Large Loan Quantum
Access S$200,000 to S$10,000,000+ depending on property value, far exceeding unsecured business loan limits.
-
No Restriction on Use of Funds
Unlike government SME loans, cashout proceeds can be used for any business purpose, inventory, payroll, renovation, expansion, investment.
-
Retain Property Ownership
You continue to own and benefit from your property’s appreciation, while putting its equity to productive use today.
-
Flexible Repayment Tenures
Loan tenures of up to 25–30 years mean manageable monthly repayments suited to your cash flow.


Eligibility Requirements for Property Cashout in Singapore
Here’s what you typically need. ThinkSME assesses your specific situation for free within 24 hours.
General Eligibility Criteria
- Property owner (individual or company-owned property accepted)
- Singapore Citizen, Permanent Resident, or Foreign National (terms vary)
- Property free from legal encumbrances or active disputes
- Minimum property value of S$500,000 (most lenders)
- Property must have sufficient equity above outstanding loans
- Personal name: comply with MAS TDSR cap of 55% of gross income
- Company name: TDSR does not apply, significantly more flexible
Documents Typically Required
- Property address
- ID copy
- Income documents
- CPF & IRAS property information
- Latest loan outstanding statement
Why Choose ThinkSME for Property Cashout in Singapore?
-
Access to 60+ Banks & Financial Institutions
Best rate guaranteed, we compare across the entire market so you never overpay.
-
Dedicated Property Cashout Advisors
Expert guidance tailored to your property type and business goals, not generic advice.
-
Full In-House Corporate Services
We handle your accounting, secretarial, and grants while securing your loan.
-
Free Eligibility Assessment within 24 Hours
Know your options before committing to anything, zero cost, zero obligation.
-
Grant Advisory Integration
Maximise EDGE grants alongside your cashout strategy.


Questions Property Cashout Singapore
What is property cashout in Singapore?
Can I use my HDB flat for cashout refinancing in Singapore?
How much can I borrow through property cashout in Singapore?
What is the interest rate for property cashout loans in Singapore?
How long does property cashout approval take in Singapore?
Can I use property cashout proceeds for my business?
Ready to Unlock Your Property's Equity?
Get a FREE, no-obligation property cashout assessment from ThinkSME today.